Smart Tools & Money Hacks for Everyday Americans
Discover practical smart tools and money-saving hacks for everyday life, from price comparison and subscription management to AI productivity tools, budgeting, and automated savings.
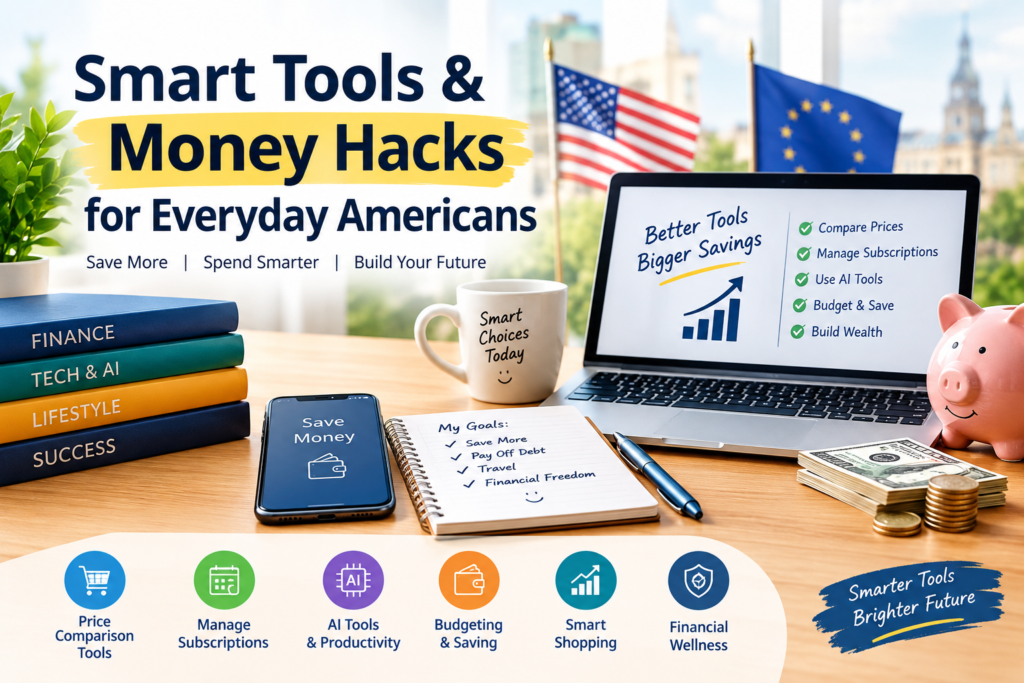
Saving money does not always require making major lifestyle changes. In many cases, small improvements in the way you shop, work, manage subscriptions, and use technology can make a noticeable difference over time.
At the same time, new digital tools are making it easier to compare prices, organize finances, automate repetitive tasks, and find better ways to manage everyday expenses.
Here are some practical money-saving ideas and smart tools that can help households in the United States and Europe make better everyday financial decisions.
1. Use Price Comparison Tools Before Buying
Prices for the same product can vary considerably between retailers. Before making a purchase, compare prices across several stores and check whether shipping, taxes, or additional fees change the final cost.
Browser extensions and price-tracking services can also help identify price drops and historical pricing trends.
For expensive purchases, waiting for a sale can sometimes make a bigger difference than using a small discount coupon.
2. Review Your Recurring Subscriptions
Streaming services, cloud storage, apps, memberships, and other subscriptions can quietly become a significant monthly expense.
Review your bank or card statements and make a list of recurring payments. Ask yourself:
- Do I still use this service?
- Am I paying for multiple services that do similar things?
- Is there a cheaper plan?
- Can I switch to an annual plan if I know I will use it?
Canceling services you rarely use can create recurring savings every month.
3. Use AI Tools to Save Time
Artificial intelligence is increasingly useful for everyday tasks.
Depending on the tool, AI can help you summarize information, organize notes, create drafts, analyze documents, plan trips, compare options, or automate repetitive work.
The financial benefit is not necessarily that AI directly makes you money. In many cases, its value comes from saving time and helping you complete tasks more efficiently.
Always review AI-generated information before using it for financial, legal, medical, or other important decisions.
4. Turn Your Shopping List Into a Budget
Instead of shopping first and calculating the total afterward, set a spending limit before you begin.
For groceries and household purchases, create a list and divide it into:
- Essential items
- Planned purchases
- Optional items
This simple system can reduce impulse purchases and make your monthly spending easier to monitor.
5. Check Your Bills Regularly
Do not assume that recurring bills are always correct.
Review bills for internet, mobile service, insurance, utilities, and other household services periodically. Look for unexpected fees, price increases, duplicate charges, or services you no longer need.
If your provider has increased its price, check whether another plan or provider offers a better deal for your needs.
6. Automate Your Savings
Automation can make saving easier because you do not have to remember to transfer money every month.
Depending on your financial situation and the options available through your bank, you may be able to schedule an automatic transfer shortly after receiving your income.
Even a relatively small recurring amount can build into meaningful savings over time.
7. Be Careful With “Buy Now, Pay Later”
Buy-now-pay-later services can make purchases feel more affordable because the cost is divided into smaller payments.
However, smaller payments do not necessarily mean a purchase is affordable.
Before using these services, understand the repayment schedule, fees, interest where applicable, and consequences of missed payments. Treat installment payments as part of your overall budget rather than as extra spending capacity.
8. Use Free Digital Alternatives
Before paying for software, apps, templates, or online services, check whether a free or lower-cost alternative meets your needs.
For example, free productivity, note-taking, document-editing, communication, and budgeting tools may be sufficient for basic personal use.
The goal is not to avoid paying for useful services. It is to make sure you are paying for features you actually need.
9. Track Your Spending for 30 Days
One of the simplest ways to understand your finances is to track every expense for one month.
You do not need an elaborate system. A spreadsheet or budgeting app can be enough.
At the end of the month, divide your spending into categories such as:
- Housing
- Food
- Transportation
- Shopping
- Entertainment
- Subscriptions
- Bills
- Savings
You may discover recurring expenses that are easy to reduce.
10. Focus on the Biggest Expenses First
Small savings are useful, but major expenses usually have a greater impact on your budget.
For example, reducing an expensive recurring bill, refinancing when appropriate, choosing a more economical vehicle, or changing an unnecessarily expensive subscription plan may save more than constantly searching for small coupons.
Look at your largest monthly expenses first and identify where realistic changes are possible.
Final Thoughts
Smart money management is not about avoiding every purchase or constantly searching for discounts. It is about understanding where your money goes and using technology to make better decisions.
Price comparison tools, budgeting apps, AI productivity tools, automated savings, and regular subscription reviews can all help reduce unnecessary spending.
The best approach is to start with one or two changes that fit your situation and build from there. Small improvements made consistently can have a much larger impact than complicated financial systems that are difficult to maintain.
Important: Financial products, taxes, consumer protections, fees, and regulations differ between the United States and European countries. Always check the rules and terms that apply in your country before making a financial decision.